September on a calendar planner

30 September 2026

Polar Moment’s Payments Perspective: September 2026

Payments news from September 2026: the UK Payments Delivery Company launches its funding round for next-generation payments infrastructure; Visa research values UK payments innovation at £3.8bn; the FCA opens its stablecoin and crypto authorisation gateway; the ECB goes live with Pontes; and Decathlon starts to accept Wero.

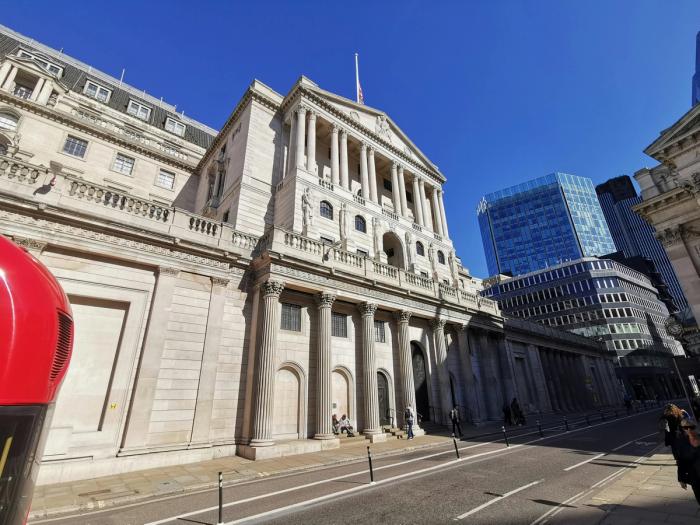
The Bank of England

UK Payments Delivery Company Launches Funding Round

The UK Payments Delivery Company (PDC) is an industry-owned vehicle set up to provide the next generation infrastructure for retail payments. This would replace the existing Faster Payments and BACS platforms.

Nineteen banks and payment firms — including Barclays, HSBC, Lloyds, NatWest, Citi, JPMorgan Chase, Nationwide, PayPal, and Wise - currently own UKPDC. It is now starting a process to raise £50m through share sales to fund development milestones through to 2028.

Consultation on the design of the next-generation infrastructure closed for responses on 11 September. This covered only the core clearing and messaging layer, not schemes, access, or user-facing products. A high-level blueprint is expected in Q1 2027.
Read more: https://thepaymentsassociation.org/article/uk-payments-delivery-company-launches-equity-capital-raise/ (opens in a new tab)

https://www.bankofengland.co.uk/news/2026/june/rpib-launches-consultation-on-next-generation-uk-payments-infrastructure (opens in a new tab)


brown wooden shelf with books

Payments Innovation Could Boost the UK Economy by £3.8bn

A report commissioned by Visa and produced by Public First estimates that more innovation-friendly regulation of UK payments could create £3.8bn in economic value by 2030. Digital payments contributed an estimated £7.5bn to UK GDP in 2024. The report argues that further gains — including £5.1bn a year from greater SME adoption and £4bn from AI use across payments — depend heavily on maintaining consumer trust as new technology is employed.

The research found 89% of consumers are confident in digital payments generally. However, 53% would abandon a transaction that didn't feel secure. Over a third of businesses surveyed had experienced fraud in the past year. Almost a quarter paused a project as a result.

The report calls for delivery of the National Payments Vision. This is a technology-neutral approach to AI and stablecoins. The report also recommended consolidation of the Payment Systems Regulator into the FCA. The UK government said it intended to do this in April.

Read more: https://www.visa.co.uk/about-visa/newsroom/press-releases.3467380.html (opens in a new tab)


person looking at charts on a laptop

FCA Prepares for Stablecoin and Crypto Authorisation

The Financial Conduct Authority published its final cryptoasset perimeter guidance (PS26/18) on 16 September. This defined five activities that will require FCA authorisation:

  1. issuing qualifying stablecoins,
  2. operating trading platforms,
  3. dealing and arranging deals,
  4. safeguarding crypto assets, and
  5. arranging staking.

Applications can be made from 30th September until 28 February 2027. The full regulatory regime takes effect on 25 October 2027. Firms currently registered for anti-money laundering purposes or authorised under the Payment Services or Electronic Money Regulations, will still need to apply.

The Bank of England has a parallel process for stablecoins large enough to be designated "systemic". It has issued a draft code of practice: the period for comments closed on 22 September.

Read more: https://www.fca.org.uk/news/press-releases/fca-sets-landmark-crypto-rules-cement-uks-place-global-hub (opens in a new tab)


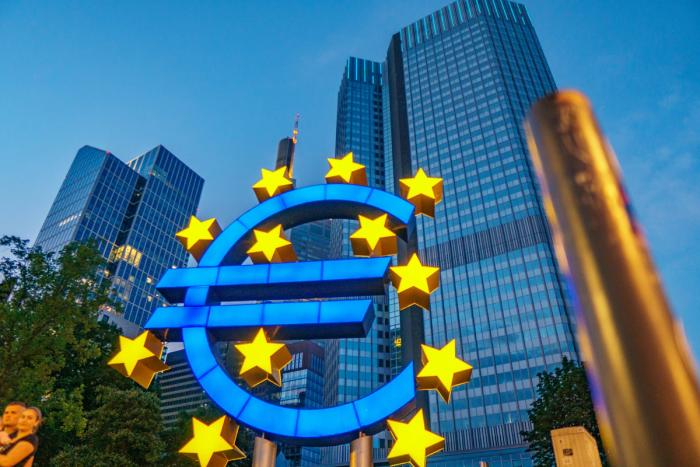
Euro symbol at the ECB

ECB Launches Pontes, its Tokenised Transaction Settlement System

Pontes is a distributed ledger technology-based settlement platform. It allows wholesale transactions in tokenised assets to be settled in central bank money. ECB President Christine Lagarde described it as marking the start of the pilot phase for the digital euro's institutional plumbing. This contrasts with the retail digital euro, which is currently going through the EU's legislative process.

The ECB is also asking online and mobile merchants to join a digital euro pilot. Participants can then give early input into the retail-facing technical specifications. A 12-month pilot is planned to start in the second half of 2027.

Read more: https://www.pymnts.com/cbdc/2026/ecb-expands-digital-euro-efforts-with-pontes-tokenization-tool (opens in a new tab)


A map of European countries with pins in it

Can Wero Crack the European Market?

The online store of Decathlon, a major sporting goods retailer in Germany, has started to accept payment through the pan-European Wero system. The Lidl/Schwarz group has also introduced the system for online payments.

Wero was developed by the European Payments Initiative (EPI). It is intended to reduce dependency on Visa and Mastercard. Wero supports account-to-account payments: funds are transferred via instant payment directly from the customer’s bank account to the merchant. Payments are authorised either through a banking app or through Wero. Users do not need to provide card details to the merchant.

EPI reports that 57 million registered users across Europe. However, a recent survey reported that only 7% of its respondents had ever used Wero.

Read more: https://www.sgieurope.com/retail/can-wero-turn-european-ambition-into-european-adoption/123135.article (opens in a new tab)